BIR E-Invoicing by December 31, 2026: A Plain-Language Guide for Philippine Businesses
The BIR's electronic invoicing deadline is no longer a moving target. On September 22, 2026, the bureau issued Revenue Memorandum Circular (RMC) No. 98-2026, confirming that covered taxpayers must issue electronic invoices by December 31, 2026.
If you've been waiting for another extension, this is the signal to stop waiting. This guide explains what the rule requires, who it applies to, and what you can do in the next 12 weeks.
How We Got Here
E-invoicing comes from the TRAIN Law and the Ease of Paying Taxes (EOPT) Act. The original rollout dates were pushed back several times. Revenue Regulations No. 26-2025, issued in September 2025, extended the compliance period to December 31, 2026.
RMC 98-2026 now lays out the operating rules ahead of that date. The Commissioner can still adjust timelines, but planning around another extension is a risk most finance teams shouldn't take.
Who Is Covered
The mandate applies to specific groups, not every business. Based on the current issuances, covered taxpayers include:
- Businesses engaged in e-commerce or online transactions (small, medium and large)
- Taxpayers under the Large Taxpayers Service
- Taxpayers using a computerized accounting system (CAS) with e-invoicing capability
- Other taxpayers the BIR designates
Summaries of RR 26-2025 also list exporters, POS system users and registered business enterprises with tax incentives. Micro taxpayers are exempt from this round, though they may adopt e-invoicing voluntarily.
Coverage rules have shifted across issuances, so confirm your classification with your accountant or Revenue District Office (RDO). Get it in writing if you can.
What Counts as an E-Invoice (and What Doesn't)
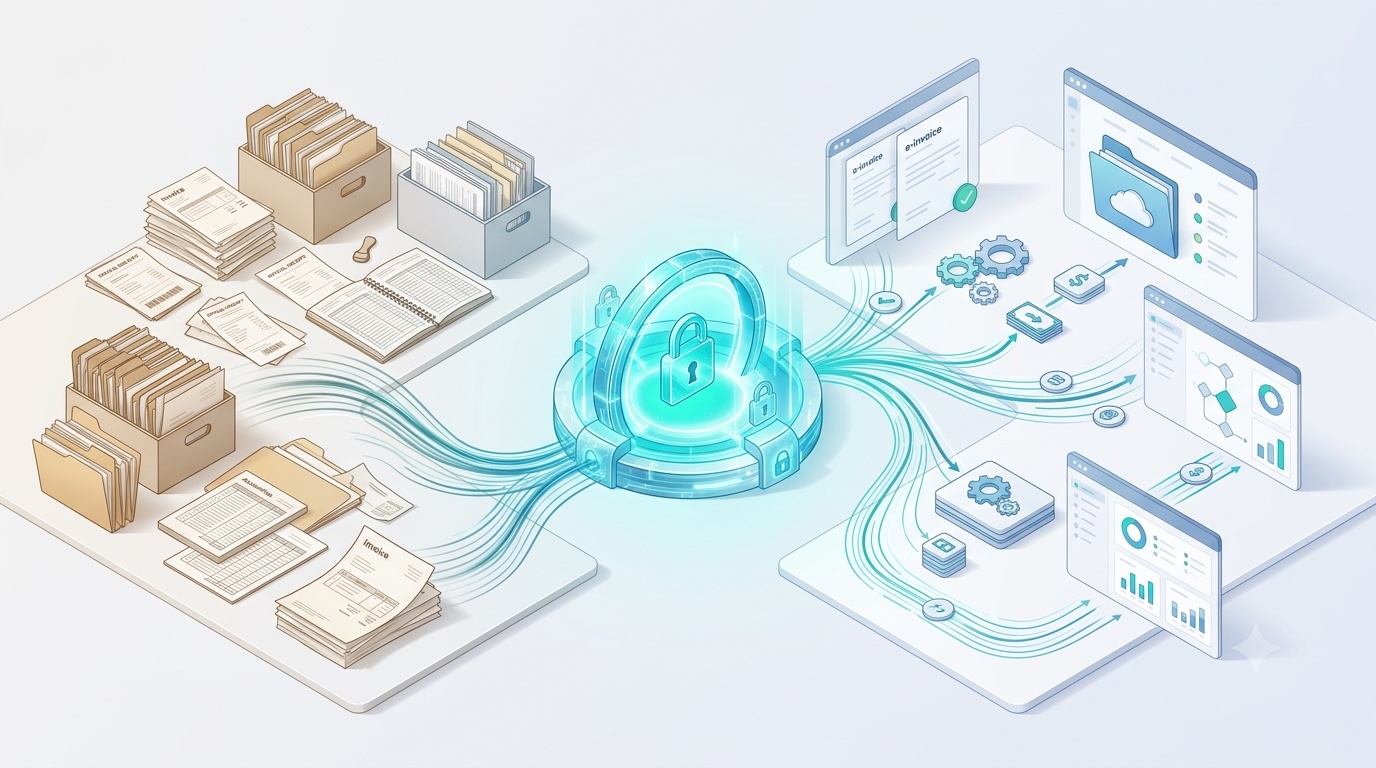
An electronic invoice is not simply an invoice sent by email. Under the rules, it must be:
- Generated by a system in a structured format
- Transmitted digitally to the buyer
- Capable of electronic extraction, processing and transmission to the BIR
That rules out several common practices:
| Invoicing practice | Counts as an e-invoice? |
|---|---|
| Invoice typed in Word or Excel, saved as PDF | No |
| System-generated invoice that is only printed | No |
| Scanned copy of a booklet invoice | No |
| Structured invoice data generated by your system and sent digitally to the buyer | Yes |
The Two Permits You Need
1. Permit to Issue (PTI) Electronic Invoice. Apply at your RDO before you start issuing e-invoices. This covers your head office and all branches, even if only one location does the covered activity.
2. EIS Certification. Your system must be certified for the BIR's Electronic Invoicing and Sales Reporting System (EIS). You have six months from PTI issuance to secure it. Failing to do so is grounds for revoking your PTI.
In practice, the PTI is the starting gun, not the finish line. Plan the certification work at the same time.
The Real Work: Your Data
Most of the effort isn't in the forms. It's in making your invoice data clean enough for a machine to read.
When we recently reviewed an e-invoice data mapping for a large company, we logged 64 findings before a single invoice could go out. Typical issues we see:
- Incomplete buyer details. Missing TINs, outdated addresses, inconsistent business names.
- Inconsistent seller details. Two company codes or branches showing different registered information.
- Tax amounts that don't reconcile. VAT on the invoice total not matching the sum of the line items, often due to rounding.
- Invoices from too many sources. A POS here, a spreadsheet there, a manual booklet for walk-ins.
- No clear owner. IT thinks finance is handling it; finance thinks the software vendor is.
None of these are new problems. E-invoicing just makes them visible.
A 12-Week Readiness Checklist
Weeks 1–2 (October)
- Confirm in writing whether you're covered, and for which entities and branches.
- Name one internal owner for the project.
- List every place your business issues invoices today.
Weeks 3–6 (Late October to November)
- Ask your software provider directly: can it produce EIS-compliant structured invoices, and is it certified or in the process?
- Clean your customer master data: TINs, registered names, addresses.
- Check that seller information matches your Certificate of Registration across all branches.
- File your PTI application at your RDO.
Weeks 7–12 (November to December)
- Run test invoices and reconcile tax amounts line by line.
- Train the staff who issue invoices, including branch cashiers.
- Map out the EIS certification timeline after your PTI is issued.
- Document a fallback procedure in case of system downtime.
Frequently Asked Questions
Is sending a PDF invoice by email enough?
No. The invoice must be structured, system-generated data, not a document created in Word or Excel.
We're a micro taxpayer. Do we need to do anything?
Not for this deadline. But if you expect to grow, choosing a system that can issue e-invoices later will save you a migration. For a broader look at SMEs, see Do Philippine SMEs Need BIR E-Invoicing?
Do all our branches need to comply?
Yes. If your business is covered, the requirement applies to the head office and every branch.
What happens if we get the PTI but not the EIS Certification?
You have six months after PTI issuance. Failing to secure certification within that window is grounds for PTI revocation.
The Bottom Line
December 31 is close, but 12 weeks is enough time if you start with the right questions. Confirm your coverage, clean your data, and talk to your software provider now.
The businesses that struggle in January will be the ones that treated this as a December task.
This article is for general information and is not tax or legal advice. Confirm your specific obligations with your accountant or RDO.